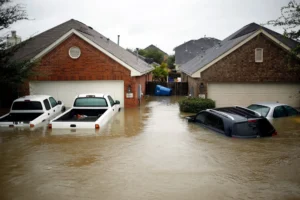
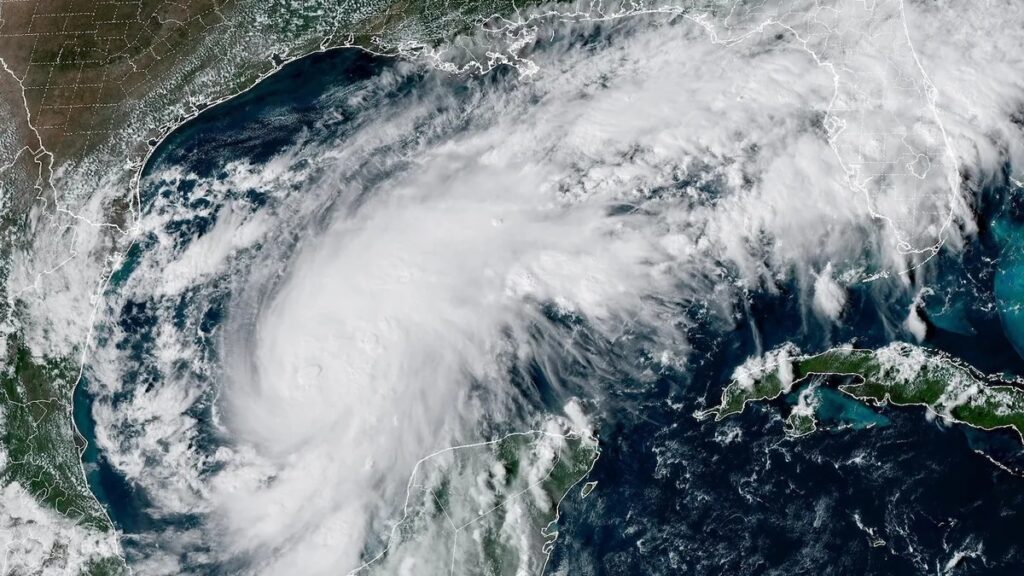
Hurricane Isaias left thousands of Northwest Florida homeowners dealing with roof damage, fallen trees, water intrusion, and difficult insurance claim decisions. As insurance claims continue to be processed, homeowners in Santa Rosa, Escambia, Okaloosa, Walton, and Bay counties may be wondering whether their insurance settlements will cover the full extent of their property damage.
According to Florida insurance industry reporting, Hurricane Isaias has generated more than 62,000 insurance claims statewide, with estimated insured losses reaching approximately $652 million.
For homeowners in Milton, Pensacola, Navarre, Pace, Crestview, Destin, and surrounding communities, understanding how hurricane insurance claims are evaluated is essential, especially when damage is extensive, repairs are expensive, or an insurance settlement appears insufficient.
The HomeOwner’s Advocate helps Florida property owners understand their insurance claims, document property damage, review settlement estimates, and pursue compensation supported by their insurance policies.
Hurricane Isaias Insurance Claims Exceed $652 Million in Florida
Hurricane Isaias made landfall near Destin, Florida, on October 9, 2026, as a Category 2 hurricane with maximum sustained winds of approximately 105 mph.
The National Hurricane Center reported wind gusts reaching 116 mph near Santa Rosa Sound and 100 mph near Pensacola, illustrating the strength of the storm conditions affecting Northwest Florida.
According to Florida Office of Insurance Regulation data reported as of October 27, 2026, Hurricane Isaias had generated:
- 62,295 insurance claims statewide
- Approximately $652.2 million in estimated insured losses
- More than 52,000 residential property claims
- 15,342 claims closed without payment
- 33,368 open claims with no payment reported
- 4,292 open claims with some payment reported
The estimated insured loss figure includes reported insurance obligations and reserves, not simply money already paid to policyholders.
These figures also include multiple insurance categories, such as residential property, commercial property, automobile damage, and other covered losses.
The totals are preliminary and may change as insurance companies continue processing claims.
What Does It Mean When a Hurricane Claim Is Closed Without Payment?
A claim closed without payment does not automatically mean the insurance company improperly denied coverage.
Some claims are closed because the damage falls below the deductible, the loss is excluded from the policy, or the insurer cannot complete the adjustment process.
However, homeowners who disagree with the insurance company’s findings should review the written explanation and supporting estimate before assuming that no additional options are available.
Which Northwest Florida Counties Reported the Most Hurricane Isaias Insurance Claims?
The highest reported claim volumes were concentrated in five Northwest Florida counties.
According to insurance reporting based on the October 27, 2026 data, the approximate county totals were:
|
County |
Reported Insurance Claims |
|
Santa Rosa County |
29,500 |
|
Escambia County |
19,000 |
|
Okaloosa County |
6,000 |
|
Walton County |
2,300 |
|
Bay County |
2,200 |
These figures include multiple types of insurance claims, not exclusively homeowners insurance claims. Higher claim volume does not necessarily indicate more severe damage to every property within a county.
Santa Rosa County: Milton, Pace, Navarre, and Surrounding Communities
Santa Rosa County recorded the highest number of reported Hurricane Isaias insurance claims in Florida.
Communities experiencing storm-related concerns include Milton, Pace, Navarre, Navarre Beach, Point Baker, Jay, Avalon, and surrounding areas.
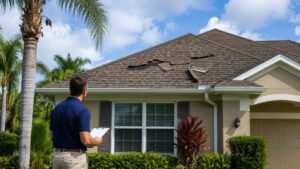
Homeowners may be dealing with damaged shingles, compromised roofing systems, fallen trees, broken windows, damaged garages, and water intrusion.
For properties in Milton and Pace, roof and structural damage should receive particular attention when reviewing an insurance estimate.
In Navarre and Navarre Beach, homeowners may also need to distinguish between wind-driven rain and flood or storm surge damage, which can involve separate insurance coverage.
Escambia County: Pensacola, Cantonment, Molino, and Pensacola Beach
Escambia County reported approximately 19,000 Hurricane Isaias insurance claims.
Communities of concern include Pensacola, Cantonment, Molino, Century, Pensacola Beach, and Perdido Key.
Homeowners may discover damaged roofing materials, broken exterior components, ceiling leaks, fallen trees, and debris-related structural damage.
Even when a home appears relatively intact, storm-related openings around roofing materials, flashing, windows, or doors can allow water to enter and damage interior building materials.
Coastal properties may require additional documentation to establish whether water damage resulted from wind-related openings or rising floodwater.
Okaloosa County: Crestview, Destin, and Fort Walton Beach
Hurricane Isaias made landfall near Destin, placing Okaloosa County directly in the storm’s path.
Communities include Crestview, Destin, Fort Walton Beach, Niceville, Mary Esther, and Shalimar.
In Crestview and surrounding inland communities, homeowners should pay particular attention to fallen trees, roof impacts, damaged exterior structures, and resulting interior leaks.
In Destin and Fort Walton Beach, insurance evaluations may involve both wind-related property damage and separate flood or storm surge considerations.
Walton and Bay Counties: Additional Storm Damage and Insurance Claims
Hurricane Isaias also generated thousands of claims in Walton and Bay counties.
Walton County communities include Santa Rosa Beach, Miramar Beach, Freeport, and DeFuniak Springs.
Bay County communities include Panama City, Panama City Beach, Lynn Haven, and Callaway.
Homeowners in these areas may have experienced wind-related roof damage, fallen debris, damaged exterior structures, interior water intrusion, or coastal flooding.
Regardless of the county, the most important question is whether the damage to your individual property has been properly documented and evaluated under your insurance policy.
5 Types of Hurricane Isaias Property Damage That May Affect Your Insurance Claim
Hurricane damage is not always immediately visible. Some losses are obvious, while others become apparent during inspections, mitigation, or repairs.
The following damage categories are particularly important for Northwest Florida homeowners.
1. Roof and Exterior Wind Damage
Does homeowners insurance cover hurricane roof damage in Florida?
Many Florida homeowners insurance policies cover direct physical roof damage caused by hurricane winds, subject to policy terms, deductibles, exclusions, and roof coverage provisions.
Common warning signs include:
- Missing, lifted, torn, or creased shingles
- Damaged metal roofing panels
- Loose flashing or roof vents
- Damaged soffits, fascia, and gutters
- Broken windows or exterior doors
- Damaged siding and garage doors
A roof does not have to collapse to sustain significant storm-related damage.
Disagreements sometimes arise when an insurer estimates limited repairs while a qualified roofing inspection identifies additional damaged components.
A licensed public adjuster can review the estimate and available documentation to help determine whether further claim evaluation is warranted.
2. Interior Water Damage and Hidden Moisture
Can I claim interior water damage after a hurricane?
Potentially. Interior rain damage may be covered when hurricane winds first damage the building and create an opening that allows water inside.
Resulting damage may include:
- Water-stained ceilings
- Damaged drywall
- Wet attic insulation
- Warped or buckled flooring
- Damaged cabinets and trim
- Moisture inside wall cavities
- Damaged furniture or personal belongings
For example, hurricane winds may damage roof flashing, allowing rainwater to enter the attic and travel into multiple rooms.
If the insurance estimate includes only the exterior roof repair, it may not fully address resulting interior damage.
Coverage depends on the cause of the water intrusion and the specific policy provisions. Damage resulting from deterioration or excluded flooding may be treated differently.
3. Fallen Trees and Flying Debris
Does homeowners insurance cover a tree falling on your house during a hurricane?
Many policies cover damage when a tree strikes an insured structure during a covered windstorm. Tree removal and damage to detached structures may be subject to separate coverage limits.
Fallen trees and flying debris can damage:
- Roof coverings and structural framing
- Exterior walls and windows
- Garages and carports
- Ceilings and interior finishes
- Doors, siding, and exterior equipment
Damage may extend beyond the visible impact area.
Homeowners should preserve photographs, inspection reports, debris removal invoices, and emergency repair receipts.
Safety comes first. Never enter an unstable structure or approach downed electrical lines to document damage.
4. Flood and Storm Surge Damage
Is hurricane storm surge covered by homeowners insurance?
Generally, no. Standard homeowners insurance policies typically exclude flooding caused by rising water or storm surge. Separate flood insurance may provide coverage, subject to its terms.
This distinction is especially important for coastal communities such as Navarre Beach, Pensacola Beach, Destin, and Panama City Beach.
A property can experience both wind damage and flooding during the same hurricane.
For example, hurricane winds may damage a roof while storm surge separately enters the lower level.
These losses may need to be evaluated under different policies or coverage provisions.
5. Structural Damage and Exterior Structures
Hurricane winds and falling trees can damage more than the roof.
Potential losses include structural framing, exterior walls, attached garages, carports, detached sheds, fences, gates, and other insured improvements.
Some damage requires a qualified contractor or engineer to determine the necessary repairs.
Coverage for detached structures and exterior improvements depends on the policy, applicable limits, and cause of loss.
How Do Hurricane Insurance Deductibles Work in Florida?
Many Florida homeowners insurance policies include a separate hurricane deductible.
Unlike a standard flat-dollar deductible, a hurricane deductible is often calculated as a percentage of the home’s insured dwelling coverage.
For example:
|
Coverage Example |
Amount |
|
Dwelling coverage |
$300,000 |
|
Hurricane deductible |
2% |
|
Dollar amount of deductible |
$6,000 |
|
Hypothetical covered damage |
$25,000 |
|
Amount after deductible |
$19,000 |
This simplified example assumes the full $25,000 is covered and does not account for depreciation, other policy provisions, or previous hurricane losses during the same calendar year.
Florida hurricane deductibles generally operate on a calendar-year basis under applicable personal residential policies.
Why does this matter?
A homeowner may receive less than expected because of the deductible, even when the insurer acknowledges covered damage.
Before concluding that your claim is underpaid, review the deductible shown on your declarations page and how it was applied.
Also review whether the insurer’s repair estimate includes all documented covered damage.
Why Are Some Hurricane Isaias Insurance Claims Closed Without Payment?
As of October 27, 2026, 15,342 Hurricane Isaias claims had been reported closed without payment.
A closed claim is not necessarily an improperly denied claim.
Possible explanations include:
- Damage below the applicable deductible
- Damage excluded under the policy
- Flood damage reported under a policy without flood coverage
- Duplicate or withdrawn claims
- Missing information or unresolved communication issues
- Disagreements over the cause or extent of damage
What should you do if your claim was closed without payment?
Request the insurer’s written explanation and compare it with your policy, photographs, inspection reports, and repair estimates.
If the explanation appears inconsistent with the documented loss, consider obtaining a professional review.
A licensed public adjuster can help evaluate the claim documentation and identify whether additional supporting information may be appropriate.
5 Signs Your Hurricane Insurance Settlement May Need Another Review
Before accepting a final settlement or signing documents that may affect your rights, consider whether the insurance estimate addresses the full documented loss.
-
Your Insurance Estimate Omits Visible Damage
The estimate may not include certain roofing components, interior finishes, damaged insulation, or other affected materials.
-
Additional Damage Was Discovered During Repairs
Contractors sometimes uncover concealed damage after removing roofing materials, drywall, flooring, or other building components.
Additional documented covered damage may support a supplemental claim.
-
Your Roof Damage Was Attributed Entirely to Wear and Tear
If you believe hurricane winds caused new damage, request the insurer’s explanation and consider obtaining a qualified inspection.
-
Your Claim Was Denied Without a Clear Explanation
Review the written denial and identify the policy provisions or factual findings relied upon by the insurer.
A denial does not automatically mean every available review option has been exhausted.
-
Your Contractor’s Estimate Is Significantly Higher Than the Insurance Estimate
Differences may involve repair scope, labor costs, material quantities, building requirements, or repair methods.
A higher estimate does not automatically establish underpayment. However, documented differences may warrant further evaluation.
What Should You Do Before Accepting a Hurricane Insurance Settlement?
If your insurance company has provided an estimate or payment, take time to understand what it includes.
- Review your insurance policy. Confirm your coverage limits, hurricane deductible, exclusions, and settlement provisions.
- Examine the insurance estimate. Review the listed repairs, quantities, materials, and pricing.
- Compare qualified repair estimates. Determine whether contractors have identified additional necessary work.
- Organize your documentation. Preserve photographs, inspection reports, mitigation invoices, correspondence, and repair records.
- Check for newly discovered damage. Report additional losses promptly and follow applicable notice requirements.
- Review any release or final settlement agreement. Understand the terms before signing documents that may limit future claim options.
Receiving an initial insurance payment does not always prevent a homeowner from seeking additional covered amounts. However, the effect of a settlement or release depends on its terms and circumstances.
Need Help Reviewing Your Hurricane Insurance Settlement?
If your Hurricane Isaias claim was denied, delayed, or appears underpaid, The HomeOwner’s Advocate can help you review the documented damage and understand your options.
Request a free insurance claim assessment from The HomeOwner’s Advocate.
Call 855-FAIR-CLAIM to discuss your property damage and claim concerns.
What Are Florida’s Deadlines for Hurricane Insurance Claims?
Florida law establishes important notice deadlines for property insurance claims.
Under Florida Statutes §627.70132, the general requirements include:
- Initial claims: Notice within one year after the date of loss.
- Reopened claims: Generally subject to the same one-year notice period.
- Supplemental claims: Notice within 18 months after the date of loss.
For Hurricane Isaias damage dated October 9, 2026, the corresponding general statutory deadlines would be:
|
Claim Type |
General Deadline |
|
Initial claim |
October 9, 2027 |
|
Reopened claim |
October 9, 2027 |
|
Supplemental claim |
April 9, 2028 |
These dates are general statutory calculations, not guarantees that a particular claim remains eligible. Policy conditions, exceptions, and other legal requirements may apply.
Homeowners should report damage as soon as reasonably possible rather than waiting until a deadline approaches.
If you are uncertain about the applicable deadline or your claim’s status, seek qualified professional guidance promptly.
How Can a Public Adjuster Help With a Hurricane Isaias Insurance Claim?
A public adjuster is a licensed insurance claims professional who represents the policyholder rather than the insurance company.
For homeowners managing complicated hurricane losses, public adjusting assistance may include reviewing the damage, evaluating repair estimates, organizing claim documentation, and negotiating supported claims within the scope of the adjuster’s license.
Property Damage Evaluation
A public adjuster can review reported roof damage, interior water intrusion, structural losses, and other potentially covered damage.
Insurance Policy and Estimate Review
Understanding coverage limits, deductibles, exclusions, and repair estimates is essential when assessing a settlement.
Supplemental Claim Assistance
When additional covered damage is discovered, a public adjuster can help document the loss and prepare supporting claim information, subject to applicable deadlines.
Denied or Underpaid Claim Assistance
When an insurer and homeowner disagree about the extent or cost of covered damage, a public adjuster can assist with preparing and presenting the policyholder’s supported claim position.
Frequently Asked Questions About Hurricane Isaias Insurance Claims
- Can I still file a Hurricane Isaias insurance claim in Florida?
Potentially. Florida law generally requires initial and reopened property insurance claims to be reported within one year after the loss, while supplemental claims generally have an 18-month notice deadline. Report damage promptly and confirm the requirements that apply to your policy.
- Which Florida counties reported the most Hurricane Isaias insurance claims?
Santa Rosa, Escambia, and Okaloosa counties reported the highest claim volumes as of October 27, 2026, followed by Walton and Bay counties. Reported claim counts include multiple insurance categories and may change as additional claims are processed.
- Does homeowners insurance cover hurricane roof and water damage?
Many policies cover direct wind-related roof damage. Resulting interior rain damage may also be covered when wind first creates an opening in the building. Coverage depends on the policy and documented cause of loss.
- What should I do if my hurricane insurance claim is denied or underpaid?
Review the insurer’s written explanation and estimate, gather photographs and repair documentation, and consider a professional claim evaluation. Additional evidence may support reconsideration or another available dispute-resolution process.
- Do I need a public adjuster for hurricane damage?
Not every hurricane claim requires a public adjuster. However, professional assistance may be beneficial when damage is extensive, estimates conflict, coverage is disputed, or the claim appears underpaid.
- Who Can Help With Hurricane Insurance Claims Near Pensacola?
The HomeOwner’s Advocate provides public adjusting and insurance claim consulting services to Florida policyholders, including homeowners in Northwest Florida. The firm offers free claim assessments for property owners who need assistance understanding or reviewing their insurance claims.
Get Hurricane Isaias Insurance Claim Help in Northwest Florida
For homeowners in Santa Rosa, Escambia, Okaloosa, Walton, and Bay counties, recovering from Hurricane Isaias may involve more than repairing visible storm damage.
Roof damage, hidden moisture, fallen trees, and structural problems can create complicated insurance claims, particularly when an insurer’s estimate does not appear to account for the full documented loss.
Whether your property is in Milton, Pensacola, Navarre, Pace, Crestview, Destin, Fort Walton Beach, Panama City, or another Northwest Florida community, understanding your insurance coverage and reviewing your claim documentation are important steps.
If your hurricane insurance claim has been denied, delayed, closed without payment, or appears underpaid, The HomeOwner’s Advocate can help you evaluate the circumstances.
Insurance coverage, claim eligibility, and settlement outcomes depend on the policy terms, documented cause and extent of damage, applicable Florida law, and individual claim circumstances. Public adjusting services do not guarantee claim approval or any particular settlement amount.